Showing posts with label Data Releases. Show all posts

Thursday, May 28, 2020

Unemployment Insurance Claims Data Shed Light on the Local Economic Impacts of the COVID-19 Pandemic in Southwest Utah


By Lecia Parks Langston, Senior Economist


“You have power over your mind — not outside events. Realize this, and you will find strength.” Marcus Aurelius

In the wake of the COVID-19 pandemic, businesses lost revenues and workers lost jobs. But because of the time it takes to collect and collate data, economists have been left without much information to quantify the economic impacts at the local level.

But there is one ray of data illumination. Claims for unemployment benefits are promptly available and provide information about a large cross section of the economy. This post will outline what light unemployment claims data sheds on the state of southwest Utah’s economy.

While not all workers are protected by unemployment insurance laws, roughly 95% of jobs are covered. This makes claims data an exceptional source of information about the economy. Not included under unemployment insurance laws are most self-employed workers, about half of agricultural employment, unpaid family workers, railroad personnel (covered separately) and many nonprofit organizations (such as churches). Also, some out-of-work employees may not have worked a sufficient work history to qualify for unemployment insurance benefits, but may file anyway. Fortunately, in this time of economic distress, the social safety nets of the unemployment insurance program, special national COVID-19 funding and social programs are working together to keep workers’ income and well-being stable.

Unemployment claimants and the unemployed; they aren’t the same


Also, keep in mind that, in addition to individuals drawing unemployment benefits, the unemployment rate includes those entering and re-entering the workforce and noncovered groups without current employment. This means the number of “unemployed” will be greater than the number of claimants. In “normal” times, only about 40% of the “unemployed” are claiming benefits. The generally reported unemployment rate also has a work-search requirement. If you haven’t made any minimal attempts to find work, you aren’t counted as “unemployed.”

Watch this Space


While this analysis won’t be updated regularly, new data will be added to the data visualization on a weekly basis allowing readers to check back for the latest information.


An Unprecedented Event


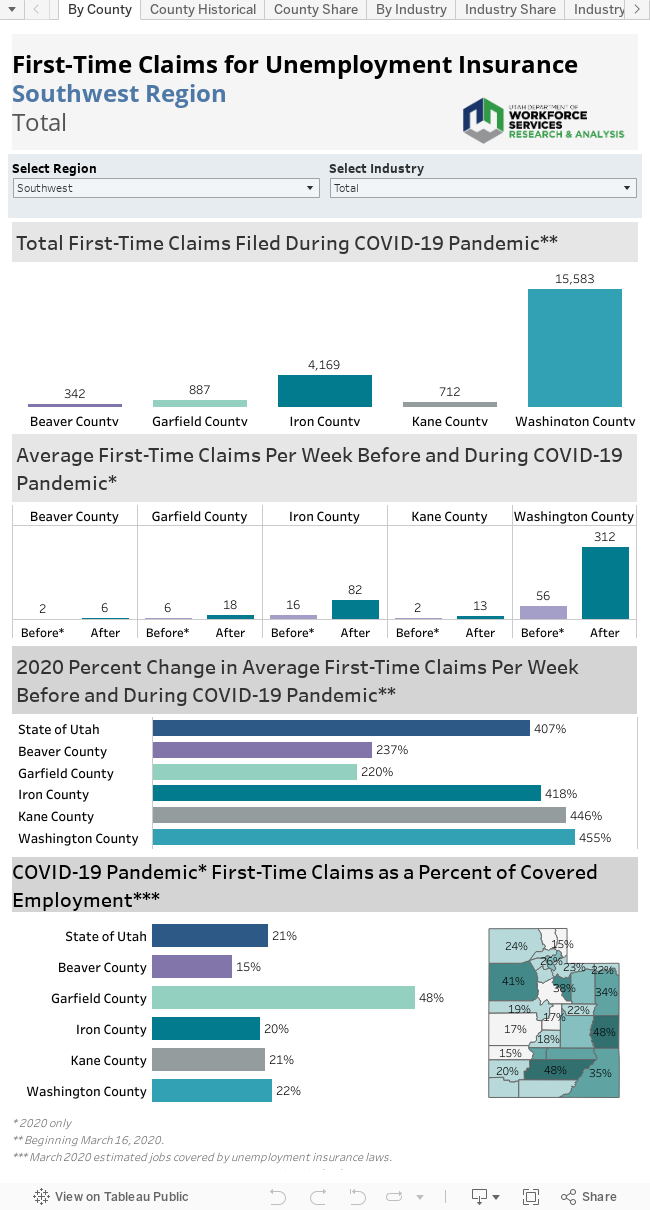
Not surprisingly, first-time claims for unemployment benefits soared in Utah and across the nation as the pandemic swept across the country. This increase is unprecedented since the creation of unemployment insurance coverage during the Great Depression. Week 12 (beginning March 16) marks the start of this unparalleled surge in claims. On a positive note, while new claims for unemployment benefits have skyrocketed in Utah, the state currently shows one of the lowest claims rates in the nation.

For most southwest Utah counties, initial claims peaked during week 13 (starting March 23) and have since tapered downward. During the peak week 13, initial claims filed totaled 2,364 in southwest Utah. In all of 2019, only 3,803 claims were filed in the region. By week 19, claims measured considerably lower but continued to run substantially greater than in previous years — even during the Great Recession.

Here’s another example of the tremendous flood of new claims. Prior to the COVID-19 pandemic, counties in southwest Utah averaged a total of 82 first-time claims per week. This time period in early 2020 included seasonally high claims weeks in January. In the weeks after, an average of 1,343 claims were filed for an almost unbelievable increase of 1,538%.

Who took the hardest hit?


Counties with a high-dependence on tourism have felt the greatest economic and employment shocks. In Garfield County, with the highest share of tourism-related employment in the state, roughly 20% of individuals covered by unemployment insurance have filed a claim — twice the rate of the state (10%) Moreover, many seasonal Garfield County workers were already drawing unemployment before the pandemic hit. In contrast, in Beaver County, only 4% of covered workers filed a claim during the pandemic. Iron (9%), Kane (10%) and Washington (11%) also felt the repercussions of upswing in furloughs and job loss.

Tourism and COVID-19


Especially in the early stages of the pandemic, this is a story of tourism-dependent industries. Almost 23% of post-COVID-19 initial claims filed in southwest Utah represented workers previously employed in accommodations and food services. In addition, the true effect of the pandemic on this industry is masked by a large number of claims classified as industry “unknown” in the early days of the claims flood. Undoubtedly, many of these claims would rightfully be classified in accommodations/food services if the appropriate information were available.

Other high-claims industries included retail trade, healthcare/social assistance (reflecting the cessation of elective procedures and visits) and administrative support/waste management/remediation (the home to temporary employment agencies). Many of these high-claim industries reflect their high share of total employment in general. In addition, they often serve the public face to face or encountered damage due to the decline in demand for travel.

The Industry Flow


While most of the high-claim industries felt the pain of the pandemic early on, other industries surged in later weeks. As the economic effects of other closures worked their way through the economy both manufacturing and transportation/warehousing proved relative latecomers to the layoffs in southwest Utah.

The High and the Low


Although accommodations/food services has generated the largest number of southwest Utah initial claims in the COVID-19 pandemic time period, in percentage terms, other industries have actually suffered more. For example, in the extremely small management of companies industry, roughly 50% of workers have filed for claims. The administrative support/waste management/remediation industries, which includes temporary employment firms, shows a first-time claims rate of 27%.

Because of its job-to-job nature, the construction industry typically accounts for 15-20% of first-time claims. However, although construction’s new claims have also increased, they have increased at a much slower-than-average rate. After the COVID-19 pandemic hit, construction contributed only about 5% of first-time claims. Ease of social-distancing and good weather have helped construction maintain employment levels. New claims measured just 3% of covered construction employment.

Only a portion of agricultural employment is covered by unemployment insurance laws. However, as companies work to keep America fed, agribusiness has laid off few employees. In Iron and Beaver counties, covered agriculture plays a notable role in the economy. However, only 1% of southwest Utah’s covered agricultural workers have filed a claim during the COVID-19 pandemic.

Public administration, educational services (including public and higher education), finance/insurance and utilities have also managed to keep a higher percentage of their workforces employed.

County by County


Beaver County


  • Prior to the COVID-19 pandemic, Beaver County averaged 2 unemployment claims per week compared to 16 new claims afterward, an increase of 834%.
  • Because of its relatively small share of hard-hit tourism-dependent employment and higher-than-average share of lightly-hit covered agricultural employment, Beaver County has shown a smaller increase in claims due to the pandemic.
  • New claims as a percent of covered employment measured just 4% — one of the lowest rates in the state.
  • As in many other areas, accommodations/food services produced the highest number of new claims, with few claims in healthcare/social assistance.
  • Unusually, arts/entertainment/recreation also contributed a high number of new claims.
  • Beaver County accounted for 2% of the Southwest Region’s new claims prior to the pandemic, but only 1% of claims afterward.

Garfield County


  • Despite having the highest percentage of leisure/hospitality employment in the state, Garfield County ranked third for the percentage of initial claims filed as a share of covered employment (20%) after the COVID-19 pandemic hit. This is likely because many seasonal workers were already drawing unemployment insurance payments when the pandemic began.
  • Prior to the COVID-19 pandemic, Garfield County averaged six first-time claims per week, compared to an average of 53 claims per week afterwards. This change represents an increase of 856%.
  • Nearly 70% of claims were filed from workers furloughed from the accommodations/food service industry. A large share of claims from the “unknown” industry category most likely originated from this industry as well.
  • Apart from retail trade, other industries contributed few new claims.
  • Seasonal claims from the colder months meant Garfield County’s initial claims actually accounted for a larger share (6%) of the Southwest Region’s figure before the pandemic than after (4%).

Iron County


  • In the weeks before the COVID-19 pandemic, Iron County averaged 16 initial claims per week. After the pandemic hit, an average of 236 claims were filed per week, marking an increase of 1,390%.
  • In Iron County, first-time claims during the pandemic measured 9% of covered employment. That places Iron County in the bottom half of a county-by-county ranking.
  • As in many counties, Iron County’s accommodations/food service industry accounted for the highest number of new claims during the COVID-19 slowdown.
  • Healthcare/social assistance and retail trade ranked second and third respectively for new claims.
  • First-time claims from the manufacturing spiked in late April.

Kane County


  • Despite having a high percentage of tourism-related employment, the county showed a middle-of-the-pack ranking for new claims as a share of covered employment (10%). As in Garfield County, many seasonal employees were already drawing unemployment benefits prior to the pandemic.
  • Prior to the COVID-19 pandemic, Kane County averaged a nominal two first-time claims per week compared with 44 claims after the pandemic struck. This increase of 1,708% ranked as the largest in the region.
  • Accommodations/food services, retail trade and arts/entertainment/recreation generated the highest number of initial claims during the pandemic.
  • Roughly 44% of Kane County’s post-directive initial claims originated in the accommodations/food services industry.
  • Kane County’s regional share of new claims held steady before and during the COVID-19 pandemic.

Washington County


  • Not surprisingly, the county with the largest employment in southwest Utah also generated the largest number of COVID-19-related first-time claims. However, its share of claims increased from 69% prior to the pandemic to 74% during.
  • Before the COVID-19 pandemic, an average of 56 initial claims were being filed in Washington County compared to an average of 994 claims in the following weeks. The pre-to-post-pandemic increase registered 1,668%
  • Initial claims for unemployment benefits filed during the pandemic as a percent of covered employment measured 11%, near the middle of a ranking of all Utah counties.
  • Although it has a higher-than-average share of employment in accommodations/food services industry, Washington County’s economy is more diverse than many less-populated counties in the state. This industry’s share of claims in Washington County measured only 19% compared to 69% in Garfield County and 44% in Kane County.
  • Here too, accommodations/food services was the source of the largest number of new claims followed by retail trade, administration support/waste management/remediation (which includes temporary employment agencies) and healthcare/social assistance.
  • Claims originating from both manufacturing and transportation surged towards the end of the pandemic time period.

Tuesday, May 26, 2020

2019 City Population Estimates Now Available


Tuesday, April 7, 2020

The U.S. Census Bureau Releases County Population Estimates for 2019

Next year, actual counts from the decennial census will be available

By Lecia Parks Langston, Senior Economist
“Any time you have population growth, there are business opportunities.” Roland Dorson
 
Hopefully, all Utahns are taking a break from COVID-19 concerns to respond (by phone, online or by mail) to their 2020 Census questionnaires (https://2020census.gov/). Since the Census results help determine how billions of dollars in federal funding are spent, accurate counts are important in order for Utah’s communities to get their “fair share.”
 
Because the actual counts are not yet available, the U.S. Census Bureau has just released the last set of population estimates for the decade. What do they show?


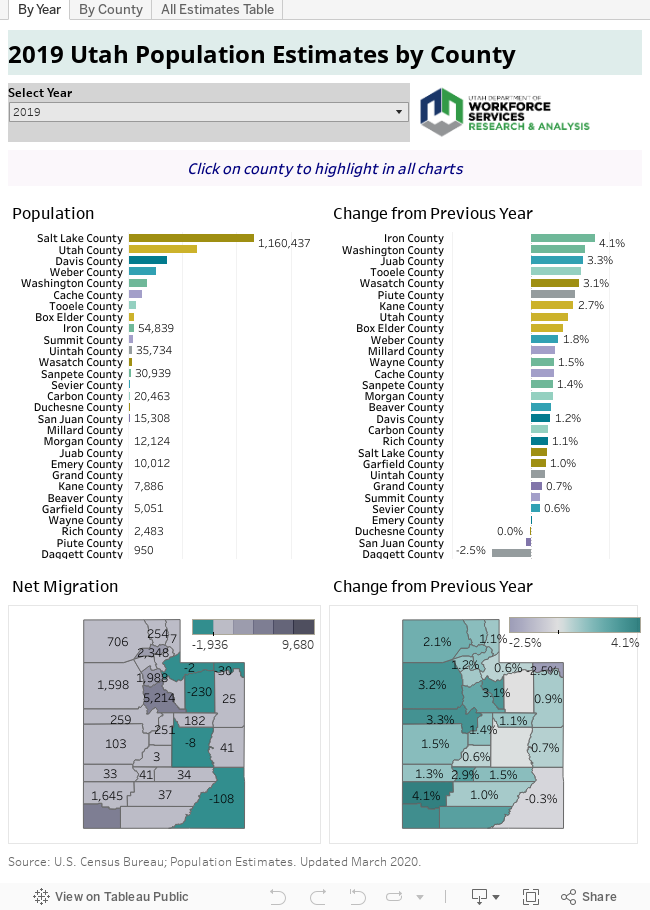
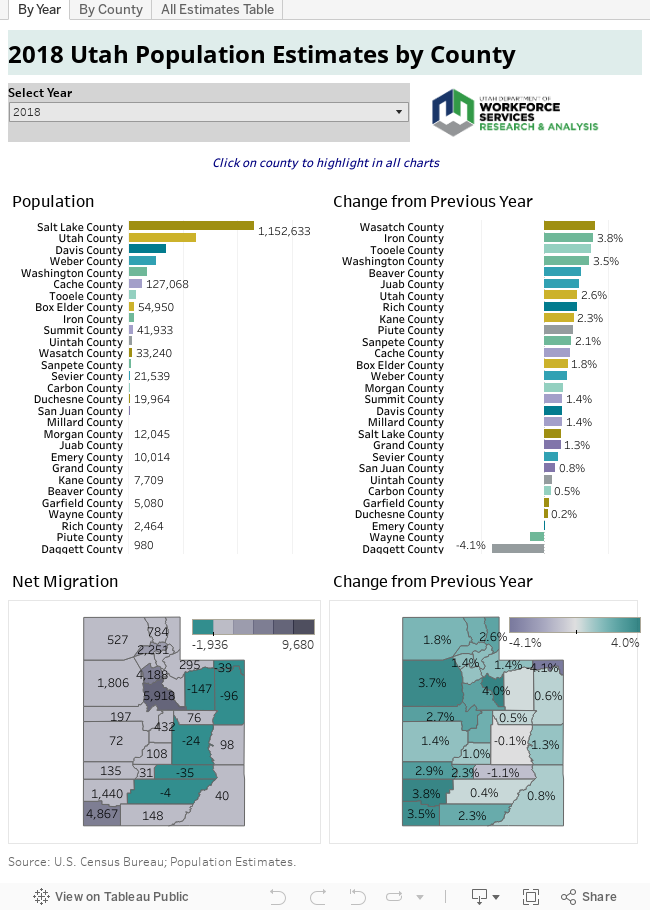
  • Iron County took the lead in population growth rates for 2019 — up by 4.1%. Following close behind was its neighbor, Washington County, with a growth rate of 3.5%.
  • Other fast-growing areas included counties at the edge of urban spread, such as Juab, Tooele and Wasatch.
  • Although Piute County saw an increase of only about 30 individuals, its small base population also resulted in a strong percentage increase (2.9%).
  • Utah County showed the highest percentage increase (2.4%) of the big-four Wasatch Front counties.
  • Estimates for both San Juan and Daggett counties suggested a decline in population, while Duchesne County’s population appeared to hold steady.
  • Utah County experienced the largest numeric gain in population — nearly 15,000 residents, followed by Salt Lake County (up about 12,000) and Washington County (up nearly 6,000).
  • Utah and Washington counties finished neck-and-neck in the race for net in-migration. Utah County’s net in-migration measured 5,200 compared to 5,100 for Washington County.
  • Several counties displayed net out-migration. Most notable on the list were Duchesne and San Juan counties. Daggett, Emery and Summit counties showed lesser out-migration estimates.
  • For its size, Utah County shows a relatively high number of births and a low number of deaths, placing its natural increase not far behind population-dense Salt Lake County.
  • Although Washington and Cache counties showed roughly equivalent numbers of births, deaths in Washington County measured much higher.
  • In 2019, Emery County experienced its first (albeit small) population growth in more than a decade.
  • Morgan County’s 2019 growth rate slipped below the state average for the first time this decade.
  • Wayne County saw its best population growth (1.5%) of the past 10 years in 2019.
  • Between 2010 and 2019, Wasatch County was the third fastest growing county in the nation. Washington County (St George, UT MSA) was the fifth fastest growing metropolitan area in the United States between 2010 and 2019. Its relatively small size contributes mathematically to a high growth rate. The Provo-Orem, UT MSA ranked ninth.
These aren’t the only estimates in town. The Kem C. Gardner Policy Institute at the University of Utah has assembled the Utah Population Committee (UPC) to reinstitute the population-estimates work previously conducted by the Utah Population Estimates Committee (UPEC). These estimates can be found here.
U.S. Census Bureau estimates use the same methodology in producing population figures for every county in the nation. Therefore, for nationwide comparisons, U.S. Census Bureau estimates may have the advantage. On the other hand, UPC population estimates have the benefit of local-analyst expertise and additional data sources.

Monday, December 17, 2018

New GDP figures will add to the local economic-analysis tool box


New GDP figures will add to the local economic-analysis tool box

By Lecia Parks Langston, Senior Economist

“We will find neither national purpose nor personal satisfaction in a mere continuation of economic progress, in an endless amassing of worldly goods. We cannot measure national spirit by the Dow Jones Average, nor national achievement by the Gross National Product.”  Robert Kennedy
As a regional economist, I’m routinely asked for gross domestic product (GDP) figures for Utah’s counties. After all, nationally, GDP is routinely tracked as an economic indicator. “Sorry,” I say, “the Bureau of Economic Analysis (BEA) doesn’t produce GDP statistics for counties (unless they are a metropolitan statistical area). But data-lovers, “the times, they are a-changin’.”
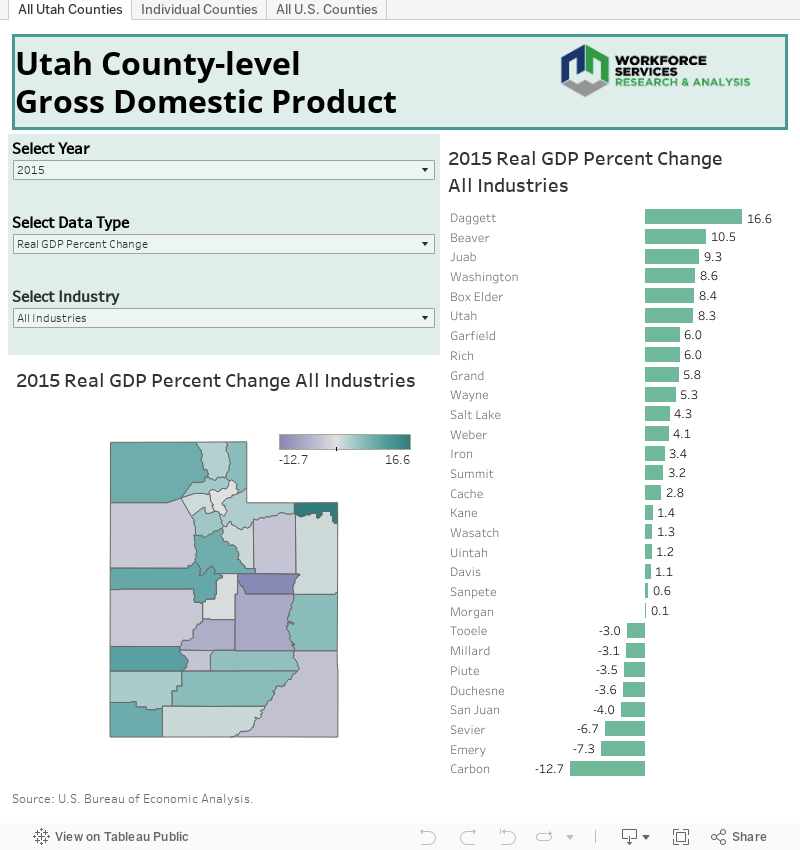
The U.S. Bureau of Economic Analysis has just released proto-type county GDP statistics for 2012 to 2015. You can explore the data in the visualization that follows.


Yes, the proto-type information is dated. However, data-users can take a first-look at the series and assist BEA by providing feedback and comments on the prototype data via e-mail at gdpbycounty@bea.gov. Official statistics are scheduled for release in December 2019.
When the official data is released, this new data will add to our ability to analyze Utah’s local economies.
What do the proto-type figures reveal? Here are a few highlights:
In 2015, eight Utah counties experienced a decline in GDP following a trend similar to 2013 and 2014.
  • Less-populated counties were most likely to experience a bout of declining GDP.
  • Daggett County, one of Utah’s smallest in both geographic size and population, showed the highest GDP growth rate in 2015 with Washington County showing the highest rate of expansion among more-populated counties.
  • It wasn’t uncommon for Utah counties to experience at least one year of GDP contraction between 2013 and 2015.
  • Not surprisingly, the vast majority of GDP is generated along the Wasatch Front.

Wednesday, September 26, 2018

State homeless report shows increase in ‘unsheltered’ individuals in Southern Utah

An annual overnight count of Utah’s homeless population in January shows the amount of individuals experiencing homelessness increased in Washington County and areas in and around Iron County, according to a report released last week. The overnight count of the state’s homeless, known as the point-in-time count, was conducted Jan. 24. The results were published Aug. 8 in a report from the Utah Department of Workforce Services.

Washington County experienced an increase of 98 unsheltered individuals this year over last, making for a total of 154, according to the report. The total number of both sheltered and unsheltered homeless individuals in Washington County is 245, according to the report, which is up from 2017’s count of 133.

For the area of Iron County – which also includes counts from Beaver, Garfield and Kane counties – the total amount of homeless individuals was 42, with 10 counted as unsheltered. This is an increase from 29 persons and no reported unsheltered in 2017. St George News

Monday, March 5, 2018

Groundbreaking set for $1.2M animal shelter in Cedar City

Cedar City is breaking ground on a $1.2 million animal shelter and adoption center. The main shelter building, originally designed as a coal storage facility, is more than 60 years old. Cedar City has purchased property near the current animal shelter where a new shelter will be located. The building will be approximately 6,500 square feet with plenty of space to meet current needs and to accommodate future growth. St. George News

Utah's Seasonally Adjusted Unemployment Rates

Seasonally adjusted unemployment rates for all Utah counties have been posted online here.

Each month, these rates are posted the Monday following the Unemployment Rate Update for Utah.

For more information about seasonally adjusted rates, read a DWS analysis here.

Next update scheduled for March 26th.

Friday, March 2, 2018

Utah's Employment Situation for January 2018

Utah's Employment Situation for January 2018 has been released on the web.

Find the Current Economic Situation in its entirety here.

For charts and tables, including County Employment, go to the Employment and Unemployment page.

Next update scheduled for March 23rd, 2018.


Thursday, June 1, 2017

Is Your Town Growing?

U.S. Census Bureau releases 2016 City Population Estimates


By Lecia Parks Langston, Senior Economist

“A city is more than a place in space, it is a drama in time” –Patrick Geddes

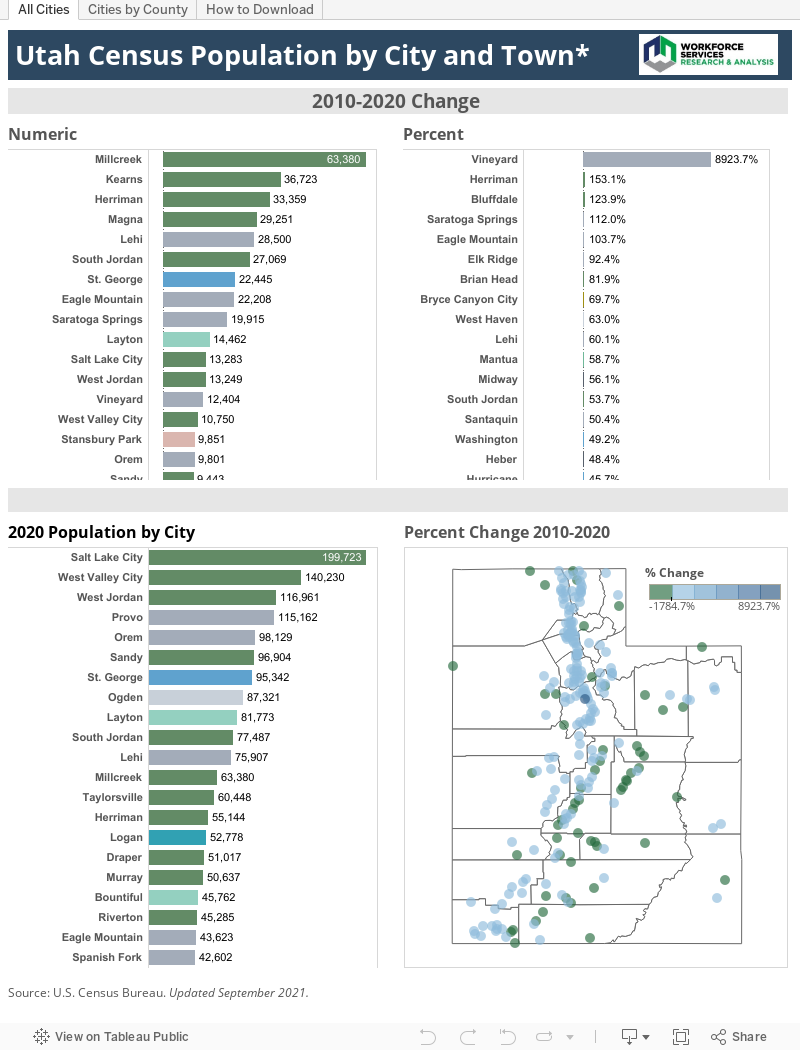
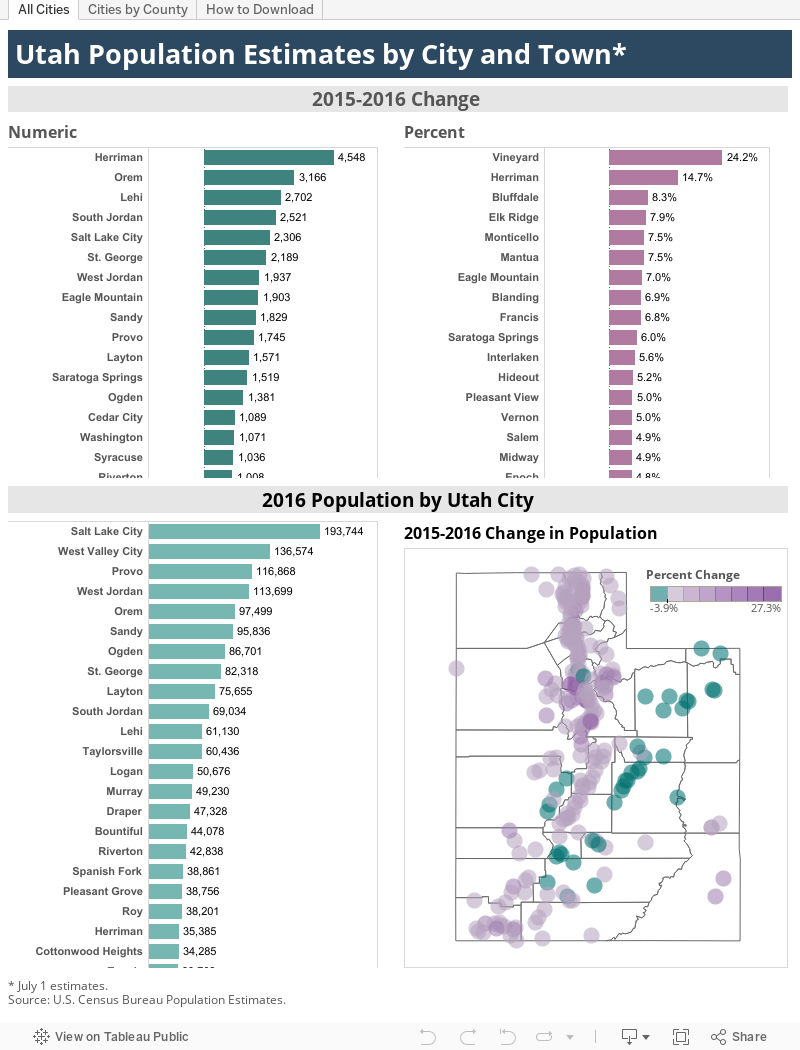
Most of Utah’s cities and towns grew in 2017, according to population estimates recently released by the U.S. Census Bureau. Lehi even ranked 11th among the nation’s fastest-growing large cities. However, not all Utah’s cities and towns experienced growth.

Use the visualization and bullet points below to explore population trends for individual townships.


• The old Geneva Steel Mill site continues to be fertile ground for population expansion. Vineyard was once again the fastest growing city in Utah. However its rate of growth has slowed dramatically since 2015. In addition, Vineyard remains relatively small in size.

• Herriman added the highest number of new residents of any city in Utah (4,550) followed by Orem, Lehi and South Jordan. All showed higher population gains than Salt Lake City — Utah’s most populous city. Herriman also showed the second-fastest rate of expansion in 2016.

• St. George was the only city outside the Wasatch Front to increase its population by more than 2,000 residents.

• The top four population-gaining cities in Utah are all located in southern Salt Lake County or northern Utah County, as the metropolitan population continued to spread outward from the large city centers. Fastest-growing larger communities also tended to be located near the Salt Lake County/Utah County border.

• Due to the nature of percent-change mathematics, several small towns (such as Monticello, Mantua, Francis, Interlaken and Hideout) showed high growth rates although their new-resident counts measured relatively low.

• The Census Bureau estimates that most of the cities and towns showing population declines were located in the Uintah Basin, Carbon County and Emery County. Declines in resource-based employment have spearheaded these population declines.

• In addition, Millard, Piute, Garfield and Wayne counties displayed a significant number of contracting townships.

• Salt Lake County remains home to five of the 10 largest cities in the state. Utah County accounts for another two in the top 10. St. George is the only city in the top-10 ranking located outside the Wasatch Front.

Thursday, April 27, 2017

Health Insurance: Who’s covered in Utah?

Census Bureau Estimates Provide Answers about Utah Health Insurance Coverage


By Lecia Parks Langston, Senior Economist

“Most Americans want health insurance.” Jacob Lew

The U.S. Census Bureau just published its Small Area Health Insurance Estimates (SAHIE) for counties and states while the national discussion on health care laws receives renewed attention. Is this a coincidence? Yes, but a timely one. This post examines how health insurance coverage for Utahns has changed and also the demographics of who has coverage and who does not.

Tracking Utahns Under 65 Years of Age

Small Area Health Insurance Estimates cover the population under 65 years of age. Of course, virtually all residents 65 and older are covered by government-provided Medicare. Because the estimates date back to 2008, two years before the signing of the Affordable Care Act (ACA), the available figures provide an indication of the effect of the ACA on health insurance coverage in Utah and its counties.
More Utahns have Health Insurance

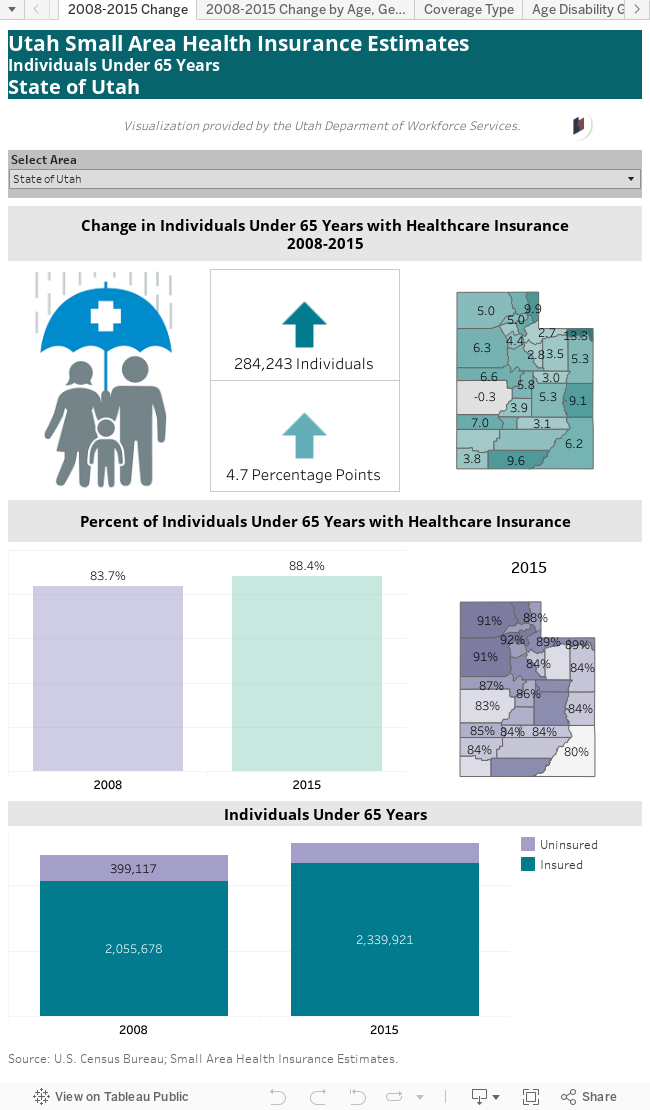
Between 2008 and 2015, the number of Utahns under 65 years old covered by health insurance increased by 284,000. Not only did the actual covered increase, but the share of non-senior population with health insurance also gained ground expanding from less than 84 percent to more than 88 percent — an increase of 4.7 percentage points.

Only Millard County experienced a very slight 0.3 percentage point decline in health insurance coverage although the actual number of persons covered increased by 113. Daggett, Rich, Kane and Grand counties showed the highest growth in under-65 coverage; each showed increases of at least 9 percentage points.

In 2015, counties in northern Utah generally showed the highest level of non-senior health insurance coverage. In Morgan, Davis, Box Elder, Tooele and Cache counties, health insurance rates top 90 percent. On the other end of the scale, rural counties in central and southern Utah display the lowest coverage. In San Juan, Millard, Duchesne and Wayne counties, health insurance rates for those under 65 measured 83 percent or less.

Those under 19 saw the greatest gains. Coverage rates for these young people increased from 87 percent in 2008 to 93 percent in 2015. Utah males experienced a larger gain in coverage between 2008 and 2015 (5 percentage points) than did females (4 percentage points), although females were more likely than men to carry health insurance in both years. Health insurance rates for those with the lowest incomes showed the most improvement (10.4 percentage points). However, their coverage shares remain roughly 10 points below average.

Wait, There’s More…

Friday, March 31, 2017

What's Your County's Population?

U.S. Census Bureau releases 2016 county population estimates.


By Lecia Parks Langston, Senior Economist

“In a region with a growing population, if you’re doing nothing, you’re losing ground.” Stewart Udall

The Census Bureau just released population estimates for counties and metropolitan statistical areas across the United States. Yes, it was just a few months ago that Utah made headlines as the fastest-growing state in the nation. So, it should come as no surprise that several Utah sub-areas also appeared on the fastest-growing lists.

San Juan County ranked as the fastest growing county in the nation with a 2016 growth estimate of 7.6 percent. Keep in mind that less than 17,000 people live in the county. In other words, a small numeric change in this less-populated county can result in a large percent change.

In addition, three Utah regions ranked among the top 20 fastest-growing Metropolitan Statistical Areas in the country. The St. George, Utah MSA (sixth), Provo-Orem, Utah MSA (seventh) and the Logan, Utah-Idaho MSA (20th) all attained top-20 status. See additional information on the estimates after the “jump.”


Pick a Number, Any Number


Because the Census Bureau actually counts the population only once every decade, these figures are estimates. Plus, they aren’t the only estimates in town. The Kem C. Gardner Policy Institute has recently assembled the Utah Population Committee (UPC) to reinstitute the population-estimates work previously conducted by the Utah Population Estimates Committee (UPEC). The estimates can be found here.

Census Bureau estimates use the same methodology in producing population figures for every county in the nation. Therefore, for nationwide comparisons, Census Bureau estimates may have the advantage. On the other hand, UPC population estimates have the benefit of local-analyst expertise and additional data sources.

Tuesday, October 18, 2016

Washington County Economic Update

April marked the fastest year-to-year nonfarm job growth in Washington County since the end of the recession. While the rate of expansion and slipped back a notch by the end of second quarter, it remained noticeably higher than the 5-percent expansion that has characterized the recovery. Continued growth at this level could signal an overheated economy. Interestingly, several industries actually lost employment. As in most Utah counties, Washington County’s saw its jobless rate increase in the first half of the year only to retreat in recent months. Strong job growth and limited unemployment insurance claims activity suggest that labor force entrants and re-entrants are temporarily inflated the unemployed totals. Construction in both residential and nonresidential sectors is up dramatically compared to last year, while gross taxable sales remained robust.

  • Between June 2015 and June 2016, Washington County added almost 4,000 new jobs for a growth rate of 7 percent. 
  • Industries making the largest employment contributions included healthcare/social services, construction, retail trade, professional/business services and transportation. 
  • Government and real estate actually showed noticeable employment contraction. 
  • Washington County showed a brief uptick in joblessness during spring and early summer as workers entered and reentered the labor market. 
  • The county's jobless rate as returned to its previous level in recent months, measuring only 3.7 percent in August 2016. 
  • New claims for unemployment insurance followed a seasonal pattern in the eight months of 2016 and provide no signs of large lay-offs. 
  • Retail trade, professional/business services and leisure/hospitality services (all with seasonal or temporary characteristics) have generated the largest numbers of first-time claims so far this year. 
  • Not only did employment increase at a rapid rate, the county’s second quarter 2016 average monthly wage improved by a robust 4.5 percent over the previous year. 
  • Both nonresidential and residential permitting increased substantially during the first eight months of 2016. 
  • New home permits are up 39 percent over last year, although a portion of the new permits are for much needed apartments. 
  • Washington County’s gross taxable sales increased by a robust 8 percent between the second quarters of 2015 and 2016. 
  • Retail sales proved particularly strong with auto dealers leading the way. In addition, tourism-related accommodations and food service sales increased decidedly.

Kane County Economic Update

Kane County job growth eased back a bit in second quarter, but still remained moderate. Job losses in a few industries cooled overall expansion. Despite employment expansion and the lack of unseasonal unemployment insurance claims activity in the first half of the year, joblessness edged up slightly during spring and early summer as workers entered or reentered the labor market. However, joblessness has retreated in recent months. Nonresidential construction permitting has surged in 2016, while the value of newly permitted homes slipped. However, a good labor market performance combined with strong sales expansion points to a healthy Kane County economy.


  • Kane County’s nonfarm employment increased by 2.6 percent between June 2015 and June 2016, adding nearly 100 net new jobs. 
  • The major industries were split into job-gaining and job-losing camps with mining, construction, manufacturing and financial activities making the strongest games. 
  • The largest job –losing industries included leisure/hospitality services and government. 
  • As in many Utah counties, joblessness in Kane County has crept up in spring and early summer only to decline in recent months. 
  • At 3.8 percent (August 2016), the county’s unemployment rate remains low. 
  • First-time claims for unemployment insurance seem to be following a seasonal pattern with no cyclical disturbances. 
  • The seasonal leisure/hospitality services industry has generated the highest number of new claims so far in 2016. 
  • However, construction, retail trade and mining also showed a significant number of claims. 
  • After a lull in wage growth earlier in the year, Kane County produced a strong 4.6 year-to-year change in its average monthly wage in second quarter 2016. 
  • The permitting of hotels/motels, a professional building and a retail establishment helped drive up Kane County nonresidential construction values for the first eight months of 2016. 
  • However, while the number of newly permitted home is up, the value of those permits dropped substantially from 2015. 
  • Gross taxable sales jumped up 10 percent between the second quarters of 2015 and 2016. 
  • A dramatic increase in sales in the accommodations industry proved the primary factor in this very strong expansion.
  • Iron County Economic Update

    Iron’ County’s labor market heated up in the second quarter of 2016. Keep in mind that this scorching level of job growth is not sustainable and should be watched for signs of overextension. Also, several industries experienced job losses. Nevertheless, the current employment gains mark a welcome respite from earlier years. As in most Utah counties, joblessness ticked up in spring and early summer only to subside in recent months. The county’s rate remains virtually unchanged from August of last year. First-time claims for unemployment insurance showed an unseasonal increase earlier in the summer (contributing to higher joblessness), but have since abated. Construction permitting is down from last year, but only because permitting in 2015 measured unusually high. Gross taxable sales rounded out this bright economic picture with a health performance.

    • Iron County added nearly 1,100 new jobs between June 2015 and June 2016 for a sizzling growth rate of nearly 7 percent. 
    • Retail trade, government, leisure/hospitality services, healthcare/social services and construction all contributed at least 100 positions each to the overall job improvement. 
    • However, not all industries shared in the employment joy. Information, mining and wholesale trade all lost notable numbers of jobs. 
    • Joblessness increased in spring and early summer as layoffs took their toll, but has rolled back somewhat in recent months. 
    • In August 2016, the county’s unemployment rate measured 4.4 percent, roughly equal to a year ago. 
    • First-time claims for unemployment insurance measured noticeably higher than average during the summer months, but have since subsided. 
    • Construction has generated the largest number of new claims so far this year as projects have come to a close. 
    • However, professional/business services (which includes temp agencies), retail trade and leisure/hospitality services also experienced strong claims activity. 
    • After stalling somewhat earlier in the year. 
    • Iron County’s average monthly wage resumed its upward trend with 3-percent growth between the second quarters of 2015 and 2016. 
    • Iron County’s construction permit values showed a significant decline for the first eight months of 2016 due to the comparison with usually high nonresidential permitting in 2015. 
    • On the other hand, homebuilding is up significantly from last year. 
    • Gross taxable sales also showed strong improvement with a second quarter year-to-year increase of nearly 8 percent. 
    • Sales gains in retail trade proved particularly robust.

    Garfield County Economic Update

    Garfield County’s employment levels failed to demonstrate steady improvement as 2016 progressed. Despite some brief signs of progress, by the end of second quarter, jobs showed continuing contraction. Joblessness edged up for the first half of the year only to slip back down in July and August. The late summer improvement may signal better news on the jobs front. However, due to the seasonal nature of the economy, the county’s always high unemployment rate measures more than double the state average. On the other hand, first-time claims for unemployment insurance show no signs of nonseasonal activity. Gross taxable sales provide the best economic news with more than two straight years of expansion.
    • Between June 2015 and June 2016, Garfield County’s nonfarm jobs dropped by roughly 2 percent, representing a decline nearly 60 positions. 
    • Employment contraction in public education and transportation accounted for the lion’s share of job losses although leisure/hospitality services and construction took job hits as well. 
    • Healthcare/social services, manufacturing and retail trade added notable numbers of new positions but these gains were not enough to offset other losses. 
    • Garfield County’s already high jobless rate edged up in the first half of the year only to edge down in recent months. 
    • In August 2016, the county’s unemployment rate registered 8.4 percent. 
    • The seasonal nature of the Garfield County’s labor market results in a perennially high jobless rate. 
    • So far in 2016, first-time claims have followed a seasonal pattern with no sign of cyclical distress. 
    • Although Garfield County’s average monthly wage continues to increase, improvements are minor. 
    • Between the second quarters of 2015 and 2016, the average wage increased by less than 2 percent. 
    • Gross taxable sales continued as the brightest spot in the Garfield County economy. 
    • The second quarter year-over gain measured a robust 6 percent. 
    • Sales in the accommodations industry generated much of the additional sales with retail trade improving as well.

    Beaver County Economic Update

    Beaver County’s recent economic indicators are dominated by layoffs in mining. The notable decline in the county’s nonfarm job totals can be traced primarily to mining contraction. In addition, these layoffs have driven up the area’s unemployment rate by roughly 2 percentage points. Claims for unemployment insurance have returned to more customary levels. In addition, construction permitting is off dramatically from last year. The brightest spot in this otherwise gray portrayal was a healthy increase in gross taxable sales.

    • Beaver County’s nonfarm employment dropped by roughly 140 jobs between June 2015 and June 2016, representing a year-to-year decrease of almost 6 percent. 
    • Layoffs in mining constituted the majority of lost employment. Leisure/hospitality services, construction and retail trade all added notable numbers of new jobs, but the gains did not prove sufficient to counteract mining’s declines. 
    • Most other major industries each shed a few jobs. 
    • Beaver County's unemployment rate shot up to 5.7 percent in August 2016 reflecting the significant layoffs in mining. 
    • The jobless rate is up nearly 2 percentage points from last year. 
    • Mining layoffs also drove up first-time claims for unemployment insurance in May and June, but claims have returned to a more normal level in the autumn months. 
    • Mining and construction have accounted for the vast majority of unemployment claims so far this year. 
    • Beaver County’s average monthly wage continued to slowly increase with a healthy 4-percent gain between second quarter 2015 and second quarter 2016. 
    • Construction permitting for the first eight months of 2016 pales in comparison with 2015 because of the large utility projects authorized in that year. 
    • However, residential building seems to have slowed dramatically as well. 
    • Beaver County’s second quarter 2016 gross taxable sales showed a healthy 3-percent year-over increase. 
    • Sales in retail trade, in particular at building/garden stores, contributed much of the expansion. 
    • Even a significant dip in manufacturing investment expenditures couldn’t offset the strong retail gain.

    Monday, October 17, 2016

    Show Me the Economy

    New Occupational Projections Available

    Mark Knold, Supervising Economist
     
     “The government knows everything about everyone.” 

     Fortunately, that statement is not true. Yet society still looks to the government to provide answers to comprehensive and complex questions that have their foundation within individual decisions and activities. One subject frequently directed toward the government is individual-level information about the economy — particularly, what occupations are in demand, what occupations pay well and have lucrative outlooks, and ultimately, what occupation(s) should I build my career upon?

    It takes the accumulation of a wide array of individual information to answer these questions. Employers provide the foundation information about the occupations they employ. Jobs are held by individuals, but employers provide the profile information about the job itself, not any particular individual.

    Since society desires to profile such a broad spectrum of the economy — occupational profiles and the occupational distribution within the economy — only government is in the unique position to collect, analyze and provide answers for said desire. Yet, no government program or regulatory agency mandates any comprehensive occupational reporting from individuals or businesses. Therefore, government attempts to fill the void with an ongoing, robust and voluntary survey of employers — a survey where employers are asked to provide details about their various occupations, including descriptions, quantities, wages/salaries and location. Through this survey emerges an occupational portrait of an economy.

    The U.S. Bureau of Labor Statistics (BLS) structures and funds the survey, yet the individual states conduct the survey. Under BLS administration, all states use the same methodology; therefore, occupational profiles are comparable across states.

    Through this survey, analysts discover how industries are populated with various occupations. Accountant is an occupation, yet accountants can be found across many different industries. Other occupations may be more exclusive to certain industries; for example, doctors are largely found only in the healthcare industry. One of the survey’s products is that industries can be profiled with their general mix of occupations. This is called an industry’s occupational staffing pattern.

    This brings us back to the original questions: what occupations are in demand, what occupations pay well and have lucrative outlooks, and ultimately, what occupation(s) should I build my career upon? The foundation is to make informed forecasts about how industries will expand/contract over the next 10 years. By applying existing occupational staffing patterns to each industry’s projected change, a trained economic analyst can then make an extrapolation about how occupations will correspondingly increase/decrease. Knowledgeable analyst judgment further refines the occupational expectations, such as knowing an occupation will grow faster than in the past, with the result being a set of occupational projections that accumulate to profile a state or regional economy.

    A new set of occupational projections are done every two years to keep the information fresh even though economies do not change dramatically in short order. Because of slow change, updated occupational projects generally continue the overall message of preceding occupational projections. But economies do modify with time, and therefore, subtle changes will arise with each new set of occupational projections.

    Utah’s most recent occupational projections are found here: http://www.jobs.utah.gov/wi/pubs/outlooks/state/index.html. These projections look forward to the year 2024.

    The occupational profile is structured from the general to the detailed, mimicking the structure of a family tree. First, broad occupational categories are defined, such as management or healthcare occupations; then, subcategories are defined; and finally, individual occupations are defined. Individual occupations are the heart of the occupational projections. But overall patterns and characteristics do emerge when observing the broader categories.

    While a Utah statewide profile leads the way, Utah’s local economies are not homogenous; therefore, nine Utah subregions are also profiled. Due to confidentiality restraints and statistical reliability, the amount of occupations available will diminish the smaller a subregion; but, occupations comprising the backbone of a regional economy will be available.


    Washington County and the Southwest Region 


    Lecia Parks Langston, Senior Economist

    Due to its status as a Metropolitan Statistical Area, Washington County gets its own set of survey-supported occupational projections. We also prepare a job outlook as a group for the remaining four counties in Southwest Utah (Beaver, Garfield, Iron and Kane).

    Washington County


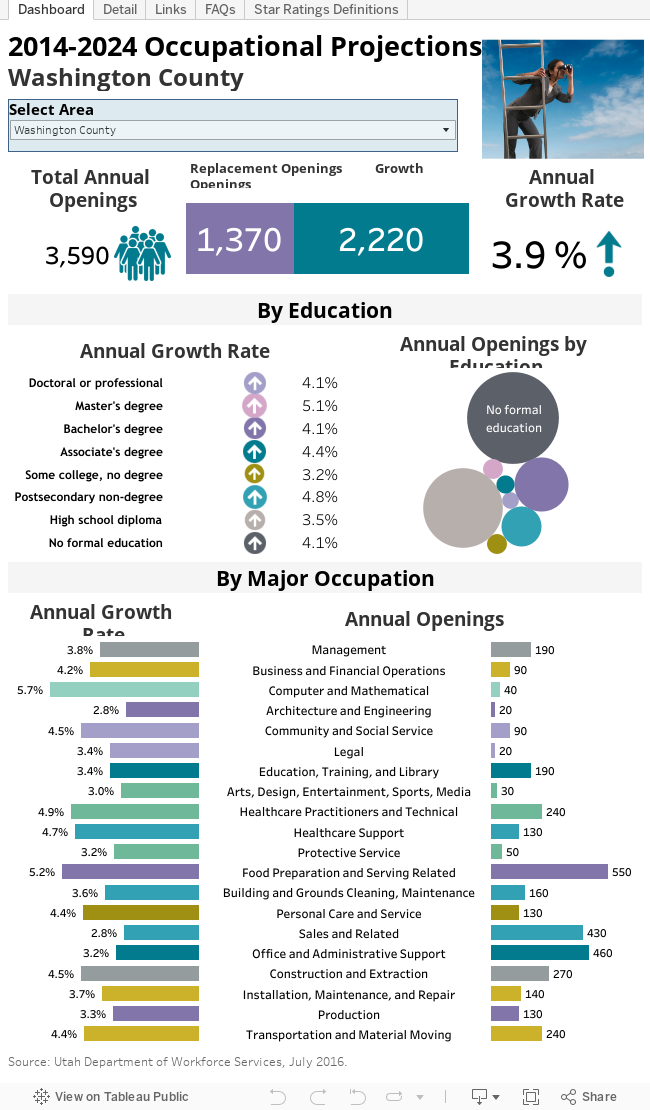
    Washington County takes top honors as the projected fastest-growing area in the state. Between 2014 and 2024, Washington County employment is expected to expand at an annual average rate of 3.9 percent, notably higher than the statewide average of 2.7 percent. That expansion should result in almost 3,600 job openings a year. Growth plays a major role in future openings with 62 percent occurring from business expansion. Replacement needs constitute the remaining 38 percent of openings. Statewide, only 54 percent of new openings are expected to arise from growth.

    With its large employment base and high replacement needs, food preparation and serving occupations are projected to create the highest number of Washington County openings. Likewise, the large employment groups of office and administrative support (e.g., clerical) and sales occupations should also generate large numbers of positions.

    On the other hand, the smaller computer/mathematical occupational group, with an annual average growth rate of 5.7 percent, is expected to show the most rapid expansion. Nevertheless, food preparation and serving jobs aren’t far behind, with a 5.2-percent annual rate of increase. In addition, both the healthcare practitioners/technical (4.9 percent) and healthcare support (4.7 percent) groups should see strong expansion as well.

    Not surprisingly, occupational groups with current low levels of employment are also expected to add fewer jobs to the economy than their much large peers. In Washington County, architecture/engineering and legal occupations will supply the smallest number of openings. The slowest growth rates are expected for architecture/engineering and sales. However, even these occupational groups show faster growth rates than the statewide average. Moreover, openings for sales occupations are high due to the large size of the occupational group and its high replacement status.

    Because many jobs in the Washington County economy currently require little education and many of these positions also have high replacement needs, jobs requiring a high school education or less are expected to account for more than 70 percent of total openings between 2014 and 2024. However, in general, jobs requiring more education are expected to expand at a faster-than-average rate.

    The individual occupations adding the highest number of openings usually belong to the major occupational groups providing the highest number of openings. In Washington County, fast food workers, retail salespersons and waiters/waitresses are expected to add the highest number of new openings. These are typically lower-paying positions. However, not all high-opening occupations in Washington County are considered low paying. General/operations managers and registered nurses are among the occupations with the highest volume of projected openings.

    In an attempt to help provide career guidance, the Department of Workforce Services has attached star ratings to most occupations. These ratings take into account both employment outlook (openings and growth rate) and wages. Among occupations with the best five-star rating, 70 percent of projected openings typically require a bachelor’s degree or higher. For more information about star ratings and detailed occupational information, see the links in the data visualization.


    The Other Southwest Counties 


    In contrast to Washington County, the remaining Southwest Utah counties are projected to grow at a slower annual average rate of 2.0 percent, notably below the statewide average of 2.7 percent. Slower projected expansion is not uncommon among Utah’s less-populated regions. Southwest Utah should generate almost 1,200 job openings each year between 2014 and 2024. Replacement needs are expected to outpace growth somewhat, providing 55 percent of total openings.

    In a pattern similar to Washington County, food preparation/serving, office/administrative support (e.g., clerical) and sales occupations are expected to provide the largest number of openings over the 10-year period. These occupational groups also maintain the highest levels of current employment.

    However, when it comes to growth rates, the four Southwest Utah counties diverge from Washington County. In Southwest Utah, the fastest growing occupational group is expected to be construction and extraction, with an annual average expansion rate of 3.7 percent. Nevertheless, both healthcare practitioners and healthcare support (2.6 percent and 3.0 percent respectively) show up among the fastest growing occupational clusters. Iron County’s heavy manufacturing presence is also reflected in strong (2.6 percent) expansion in production occupations.

    Occupational groups projected to provide few openings in Southwest Utah include computer/mathematical and architecture/engineering occupations. Life/physical/social science positions are expected to decline slightly (although replacement needs will still generate openings). Despite contributing many job openings, sales and administrative support occupations are expected to show some of the lowest growth rates along with protective services.

    Like the statewide profile, jobs with the highest current employment tend to require less education. Their large employment base coupled with high replacement needs means roughly 82 percent of employment openings between 2014 and 2024 in Southwest Utah are expected to require a high school degree or less. While growth rates by educational requirements fall in a fairly tight range, jobs typically requiring a postsecondary non-degree award should show the fastest growth while providing relatively few openings.

    As in Washington County, individual occupations in Southwest Utah projected to generate the largest number of openings are generally categorized in the occupational groups with the highest current employment. Cashiers, fast food workers, retail salespersons and waiters/waitresses are expected to show the highest number of openings in Southwest Utah. Of course, many of these positions pay lower-than-average wages. However, general/operations managers and carpenters will also provide a high level of openings.

    In Southwest Utah, five-star jobs with the best employment outlook and wages run the gamut from supervisors and managers to truck drivers and accountants. For more information about star ratings detailed occupational projections, remember to check out the links in the data visualization.

    Monday, May 23, 2016

    Most Southern Utah cities show population growth in 2015

    The U.S. Census Bureau releases 2015 population estimates for cities 

    By Lecia Parks Langston, Senior Economist 

    “I come from a small town whose population never changed. Each time a woman got pregnant, someone left town.” Michael Prichard

    The U.S. Census Bureau just released 2015 population estimates for cities and towns. In the visualization below, you can check out the estimates for your own Utah hometown. Use the “Cities by County” tab to easily locate a particular township.


    While most cities in Utah expanded during 2015, they presented a wide variety of growth experiences.

    • The old Geneva Steel Mill site has proved fertile ground for population growth. Vineyard, Utah, which is located on the spot, grew by a whopping 418 percent in just one year. However, Vineyard’s population remains relatively low in the overall scheme of things with about 3,200 residents.

    • South Jordan added the largest number of persons (roughly 3,800) of any Utah city or town. South Jordan also ranked fifth in the nation for 2015 population growth (among cities with populations of 50,000 or more).

    • The top five population-gaining cities in Utah are all located in southern Salt Lake County or northern Utah County as the metropolitan population continues to spread outward from the large city centers. Fastest-growing larger communities also tended to be located near the Salt Lake/Utah County border.

    • Due to the nature of percent changes, several small towns (Ophir, Ballard, Francis, Wallsburg) showed high growth rates although their new-resident counts measured relatively low.

    • Census estimates suggest a number of towns lost population in 2015. Every town in Carbon, Emery and Wayne counties showed contraction. In addition, Kanab and Beaver City experienced notable population declines.

    • Salt Lake County remains home to five of the 10 largest cities in the state. Utah County accounts for another two in the top 10. St. George is the only city in the top-10 ranking located outside the Wasatch Front.

    Wednesday, May 18, 2016

    Health insurance coverage improving in Southwest Utah

    The Census Bureau Releases 2014 Small Area Health Insurance Estimates 


    By Lecia Parks Langston, Senior Economist 

    “Poverty and no health insurance coverage keeps the doctor away — apples have nothing to do with it.” Beryl Dov 

    The goals of the Affordable Care Act (ACA) include expanded health insurance coverage in the United States. Most of the Act’s health insurance expansion provisions went into effect January 1, 2014. The U.S. Census Bureau’s recently-released 2014 Small Area Health Insurance Estimates  provide an initial glimpse of the early outcomes of ACA on health insurance coverage. Keep in mind that health insurance coverage runs the gamut from employer-provided plans to personal insurance to government Medicaid and Medicare coverage. These estimates cover individuals under the age of 65, since those 65 and older are eligible for government-provided health insurance through Medicare.

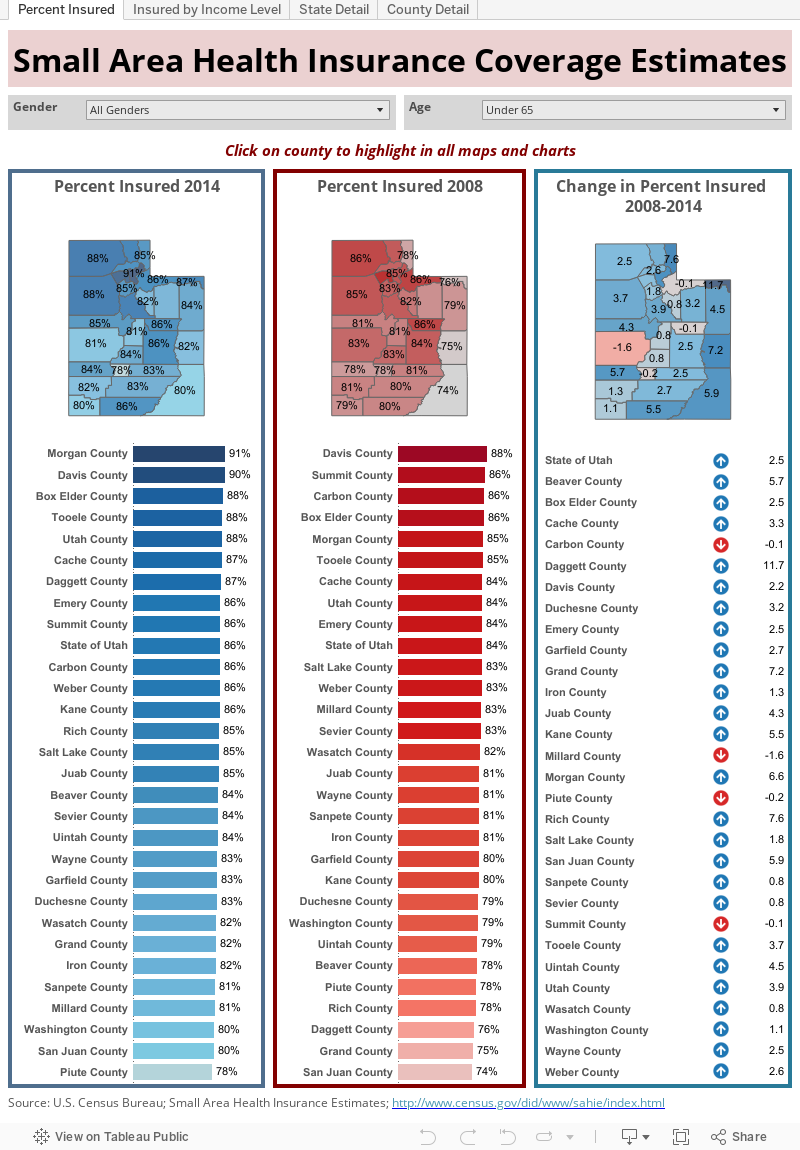
    Has health insurance coverage has expanded in the Beehive State? The percentage of individuals in Utah with health insurance coverage did increase between 2009 and 2014. In 2008, 83.7 percent of the population under age 65 had some sort of health insurance according to the Census Bureau estimates (based on the American Community Survey data). By 2014, coverage had increased by an additional 2.5 percentage points to measure 86.2 percent.


    However, while most age groups showed expanding coverage, coverage for persons between 40 and 64 actually declined. In fact, coverage contracted by almost a full percentage point for those 50 to 64 years of age. On the other hand, young people under the age of 19 saw the strongest expansion in coverage.

    Gains in the percentage of insured proved particularly strong for African Americans and Latinos. Coverage for black Utahns increased by 5 percentage points while Hispanics experienced a notable 8 percentage-point gain. In contrast, white (not Hispanic) coverage increased by only 1.8 percentage points between 2008 and 2014.

    Males (up 2.7 points) were slightly more likely than females (up 2.2 points) to experience an increase in the insured share of the population. Latino males experienced the strongest expansion, the percent of insured rose 9.1 percentage points between 2008 and 2014.

    The Census Bureau provides health-insurance categories ranging from at-or-below-138 percent of poverty to at-or-below-400 percent of poverty. Those with the lowest incomes experienced the greatest increase in coverage (up 6.6 points). However, lower-income individuals are still insured at a lower rate than their higher-income peers. For example, only 73.6 percent of those at or below 138 percent of poverty are insured compared to 86.2 percent of the general population.

    Counties in the northern part of the state tend to show the highest shares of insured individuals. In 2014, Morgan, Davis, Box Elder, Tooele and Utah counties all showed insured shares of 88 percent or higher. On the opposite end of the scale, many counties in central and southern Utah showed low insured rates. In Piute, San Juan, Washington, Millard and Sanpete counties, 81 percent or less of the population under the age of 65 had health insurance.

    While most counties shared in the state’s increasing health insurance coverage, Carbon, Millard, Piute and Summit counties all showed a slight decrease in the share of insured individuals less than 65 years of age. However, the estimated declines are well within the margin of error for these counties, which suggests that coverage might not have declined at all. In general, the largest increases in health insurance coverage occurred in small counties — Daggett, Beaver, Grand, Kane, Morgan and San Juan counties.